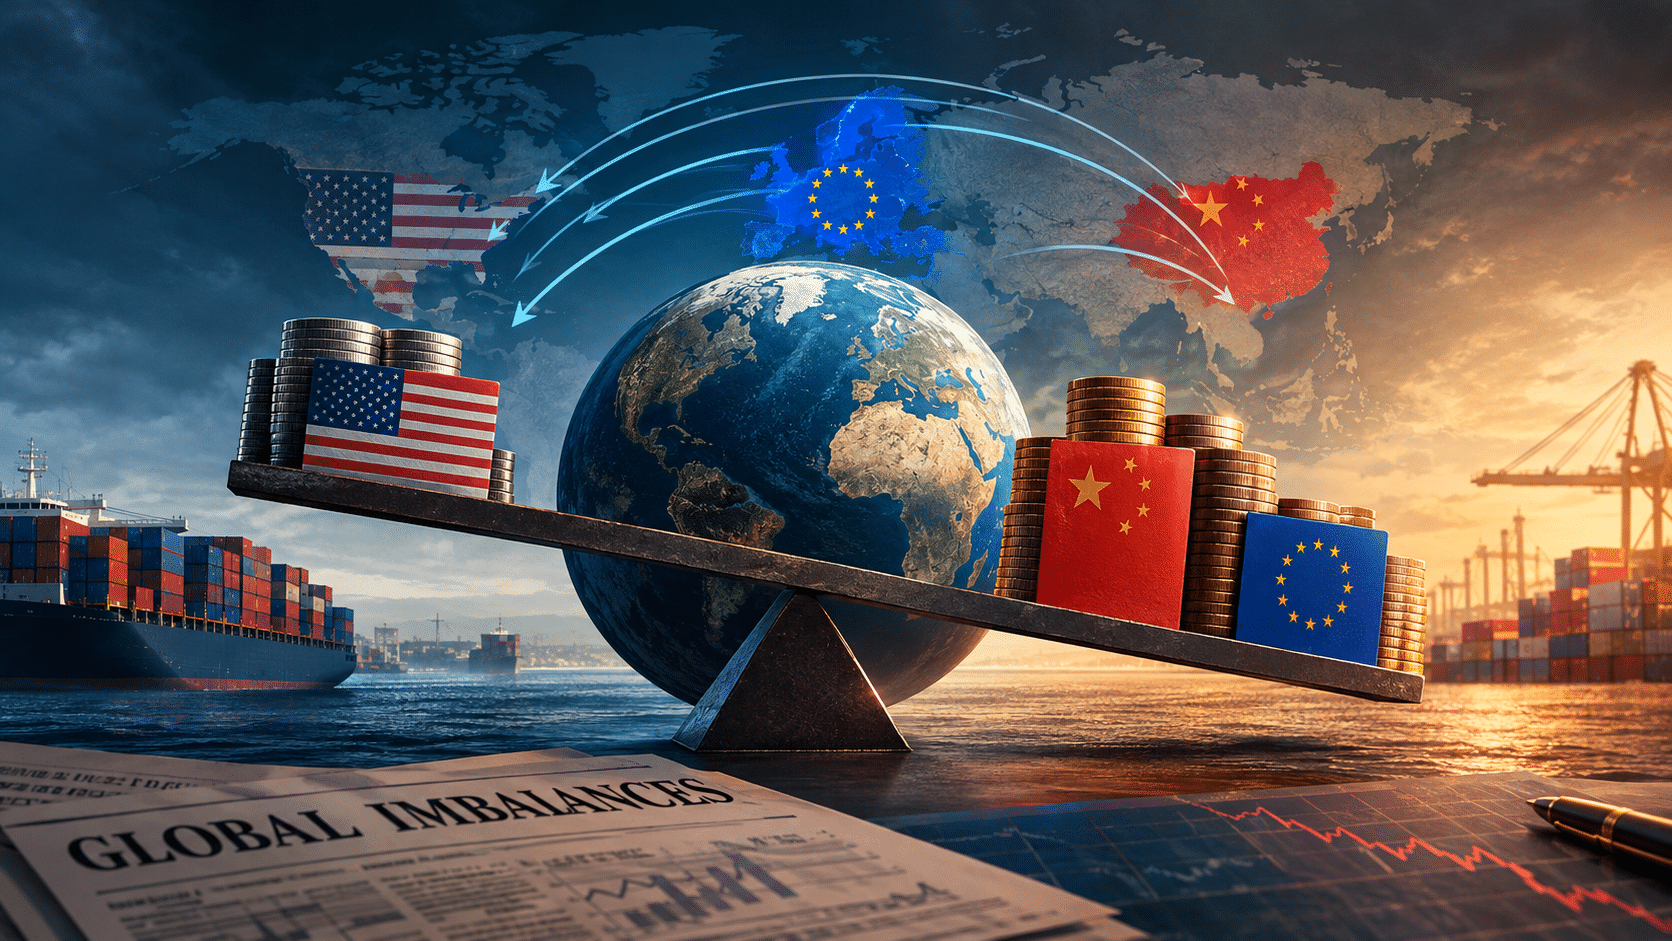


Global imbalances characterize the international economic and financial discourse. They were central to this year’s G7 Report and sparked discord at the G20 Finance Ministers’ Summit. China’s trade surplus worries the European and American leaders. US Bureau of Economic Analysis stated that net international investment was approximately minus $27.6 trillion by the third quarter of the year. It is worth noting that the last time imbalances were this high, the 2008 financial crisis followed.
The reason behind global imbalances is the misdirected focus of global economies, and imbalances are now a feature rather than a structural flaw. Ordinary saving and investment decisions lead to global imbalances—which, in simple words, is the sum of everyone’s domestic imbalances.
Why Imbalances are not Inherently Dangerous
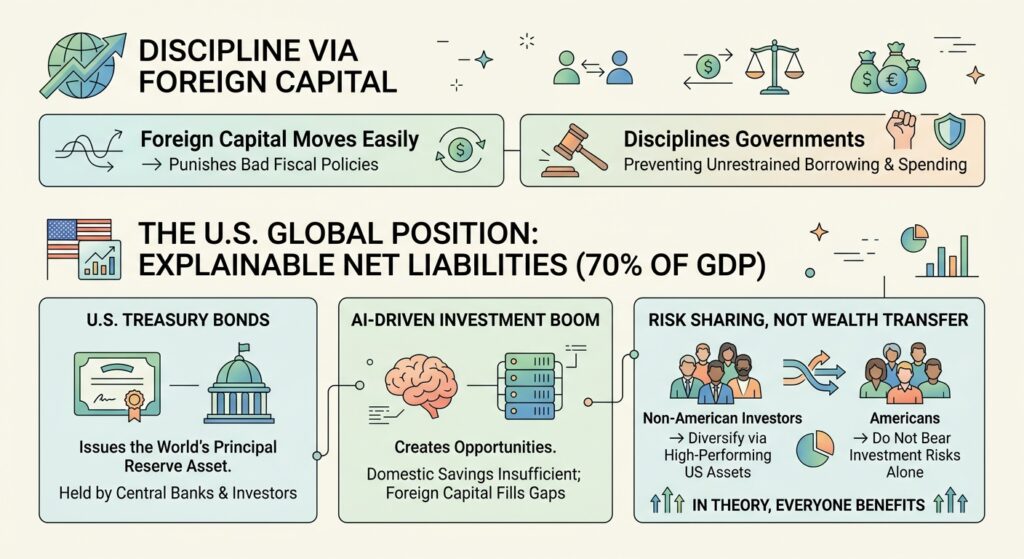
Foreign capital moves more easily than domestic capital; therefore, bad fiscal policies are punished. It disciplines governments that would otherwise borrow and spend without considering what would unfold.
Consider the United States, for example: having 70% of GDP in net liabilities, it sounds alarming, but it is explainable.
- The US issues the world’s principal reserve asset, the Treasury bond, which central banks and investors hold.
- An AI-driven investment boom has created more opportunities that cannot be funded solely by domestic savings; therefore, foreign capital fills these gaps.
This is not a wealth transfer but risk sharing. Non-American investors diversify their assets by investing in high-performing US assets. At the same time, Americans do not have to bear the investment risks alone. In theory, everyone benefits from this dynamic.
Sharing Risk is not Eliminating It.
However, this dynamic comes at a cost. Foreign investors have a flight-to-safety tendency; therefore, if they have doubts, they may distrust local laws to protect their investments. Foreign investors could retract their investments if confidence drops.
The question then arises whether it is a similar situation to 2008. The short answer is no; it is not like that. The 2008 crisis stemmed from lax financial regulation. The US economy also has a built-in stabilizer to hedge against financial crises, since its liabilities are priced in dollars and its foreign assets are in other currencies. Therefore, if investors pull back and the dollar weakens, the dollar value of the foreign assets rises, thus cushioning the overall position.
What the Imbalances Reveal
Global imbalances are a diagnostic tool that points to domestic failures. US gross debt is around 125% of its GDP, larger than its external liability position. The Treasury yields compel policymakers towards unconventional fiscal responses.
Europe, by contrast, is not generating enough investment of its own. Savings that might sustain European growth instead fund US AI infrastructure, eroding competitiveness relative to the US and China—a gap Mario Draghi’s 2024 report on European competitiveness put at roughly €800 billion a year.
China, meanwhile, spends relatively little compared with what it produces. Their savings therefore get funneled into investment at a scale that inflates the asset bubble rather than consumption. Moreover, after the collapse of its property sector, Chinese exports surged whereas the import demand stayed considerably weak, adding to the frustration of Chinese trading partners.
In both these cases, there is a solution; however, it depends on domestic fiscal policies and political will.
Diplomacy is not delivering.
Economist Hélène Rey has postulated that these separate national problems can be addressed collectively, with US fiscal consolidation offset by rising European investment and Chinese consumption. This makes adjusting both economic and political policies easier. Diplomacy recently has not delivered. G7 failed to reach a consensus on some key issues:
- US fiscal consolidation
- European structural reform
The issue was referred to the G20 finance ministers’ summit—which failed to produce even a joint communiqué. The statement issued by the G20 therefore leaned more heavily on the surplus countries than on those in deficit. Whereas Washington was explicit in its criticism of China, blaming it for the breakdown.
The pattern of blaming external factors rather than internal decisions for it has more political appeal. Political claims like “imports steal jobs” imply that a reserve-currency issuer is obligated to run deficits and that it relies on blunt tools like tariffs that treat the symptom while leaving the saving-investment gap untouched.
The Bottom Line
Global imbalance is not an imminent crisis; however, it is an early warning system. It indicates problems that could be fixed at home. Focusing more on the global dimension than on domestic reform exposes policymakers to the Risk of weakening the case for hard choices instead of strengthening it. The line from the Washington Consensus still holds: “prosperity comes from putting your own house in order, not blaming the neighbors for the state of your garden.”
Frequently Asked Questions (FAQs)
Q1: Why are global imbalances not inherently dangerous?
Foreign capital moves more easily than domestic capital; therefore, bad fiscal policies are punished. It disciplines governments that would otherwise borrow and spend without considering the circumstances that would unfold. Furthermore, the AI-driven investment boom has created more opportunities that cannot be funded solely by domestic savings; therefore, foreign capital fills these gaps. This is not a wealth transfer but risk sharing. Non-American investors diversify their assets by investing in high-performing US assets. In contrast, Americans do not have to sustain the investment risks alone. In theory, everyone benefits from this dynamic.
Q2: Are current global imbalances leading to a situation similar to the 2008 financial crisis?
The short answer is no; it is not like that. The 2008 crisis stemmed from lax financial regulation. The US economy also has a built-in stabilizer to hedge against financial crises, since its liabilities are priced in dollars and its foreign assets are in other currencies. Therefore, if the investors pull back and the dollar weakens, the dollar value of the foreign assets rises, thus cushioning the overall position.
Q3: What domestic failures do global imbalances reveal in Europe, China, and the US?
Global imbalances are a diagnostic tool that reveals domestic failures. US gross debt is around 125% of its GDP, larger than its external liability position. Europe, on the other hand, is not generating enough investment of its own. China, meanwhile, spends relatively less than what it produces. Their savings, therefore, get funneled into investment at a scale that inflates the asset bubble rather than consumption.